

From Ambition to Execution: Making Corporate Climate Action Work in India
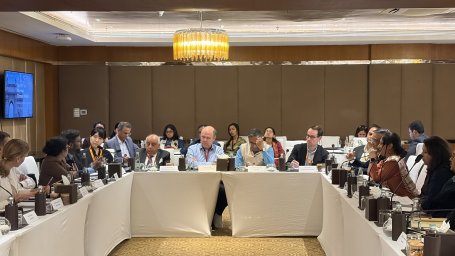
“If climate action is not economically and commercially viable, it will not be sustainable in the long run.” This observation, shared during a roundtable organised by WRI India and the Science Based Targets initiative (SBTi) during Mumbai Climate Week 2026, points to a common challenge that corporates face as they seek to scale their climate plans. Delivering ambitious decarbonisation targets requires systems, markets and partnerships that often extend well beyond an individual company’s operations.
More than 440 Indian companies have adopted science-based targets (SBTs), aligning their emissions reduction goals with climate science. But for most businesses, the biggest challenge lies beyond their own operations, in their value chains.
Emissions from upstream and downstream activities associated with suppliers, raw materials, transport and product use often account for more than 70% of a company’s greenhouse gas footprint. These are significantly harder to measure and reduce than direct operational emissions. As Indian companies move from announcing targets to implementing them, they will need enabling systems that make deeper value-chain decarbonisation possible.
Build Credible, India-Specific Emissions Measurement Systems
How emissions reductions are measured is at the heart of corporate climate action. Most emission factors are currently derived from global datasets, averaged across regions and production systems. As a result, they often fail to reflect Indian conditions.
What are emission factors?
Emission factor is a coefficient used to estimate the amount of greenhouse gas (GHG) emitted for a unit of activity, such as the amount of fuel burned, electricity consumed, or material produced.
Consider emissions factors for road freight: global averages cannot capture the variation in India's fleet composition, fuel quality, load factors and road conditions, all of which materially affect emissions per tonne-kilometre. A factor derived from European or North American fleets, with higher proportions of modern, fuel-efficient vehicles, will end up underestimating emissions from India's older, more heterogeneous trucking fleet.
Without India-specific emission factors for different vehicle classes and fuel types, companies risk misidentifying emissions hotspots, misallocating mitigation efforts and weakening progress tracking. Building India-specific emission factors should therefore be seen as a shared responsibility.
Companies can contribute operational data, research institutions can develop and validate methodologies, industry associations can help standardise approaches across sectors, and regulators can incorporate these into disclosure and carbon-market frameworks. A common India-validated dataset could be applied consistently across MRV (monitoring, reporting and verification) systems for voluntary corporate reporting, Business Responsibility and Sustainability Reporting (BRSR) disclosures and the Carbon Credit Trading Scheme (CCTS).
India’s market regulator, the Securities and Exchange Board of India (SEBI) is also moving towards mandatory, third-party verified environmental disclosures for large-listed companies through the BRSR Core with assurance-backed disclosure framework. This also creates an opportunity for companies to collectively support the data infrastructure and technical institutions needed to keep those factors updated and usable across sectors.
Embed Circular Economy Actions into Core Climate Strategy
Many Indian companies are already embracing circular economy practices, substituting scrap for virgin steel, replacing clinker with supplementary materials in cement, co-processing industrial by-products as fuel. The larger opportunity is strategic, since these actions are often pursued as efficiency or cost-saving measures, while their decarbonisation value remains under-recognised within corporate climate strategies.
Increasing steel scrap utilisation and lowering clinker ratios through slag and calcined clay substitution are among the highest-impact levers available to Indian industry. Yet only one major steel firm and eight cement companies have set SBTs. While circular economy initiatives are beginning to feature in corporate sustainability reporting, they are not always linked to measurable decarbonisation outcomes.
The shift required is not primarily technical. In many cases, the resulting emission reductions are already captured within standard GHG accounting frameworks. What is needed is a deliberate decision by companies to treat circular practices as explicit, quantifiable decarbonisation levers, with targets, investment plans and accountability mechanisms.
A useful example is the growing use of municipal solid waste (MSW) to produce refuse-derived fuel (RDF) for replacing coal in kilns. Quantifying and reporting these benefits remains difficult because India lacks standardised emission factors for RDF use in cement kilns, and RDF composition varies significantly across cities and waste streams.
Rather than waiting for standard methodologies to emerge, industry can work collectively with research institutions, standards bodies and regulators to develop robust emission factors and reporting protocols for RDF use. This would help convert a promising operational practice into a credible and scalable climate solution. The Government of India has also mandated an increase in RDF’s fuel substitution rate from 5% to 15% over six years. As the low-carbon material markets develop, companies that integrate RDF into long-term decarbonisation planning, rather than treating it as a narrow compliance requirement, are likely to be better positioned.
Policymakers can reinforce this by extending emerging procurement policies, currently focused on steel and cement, to explicitly reward companies that integrate circular economy actions.
Create Markets for Low-Carbon Industrial Technologies
For heavy industries such as steel, cement and chemicals, the decarbonisation barrier goes beyond emissions measurement. The next phase of decarbonisation is fundamentally a market-creation challenge. Many low-carbon technologies are not yet available in India at the required scale, cost or level of commercial maturity.
Industrial heat, or direct thermal energy used for manufacturing, is a case in point. Widely used in chemicals, textiles, food processing and paper manufacturing, it remains one of the least discussed aspects of decarbonisation. Unlike electricity, which has a relatively well-understood decarbonisation pathway, decarbonising high-temperature industrial heat faces constraints related to cost and technological maturity.
This creates a coordination problem across value chains. Suppliers are unlikely to invest in low-carbon production without credible demand, while downstream companies cannot reduce Scope 3 emissions at scale unless cleaner industrial inputs become commercially available.
One potential pathway to decarbonise hard-to-abate sectors is green hydrogen. India’s National Green Hydrogen Mission is targeting 5 million metric tonnes of production annually by 2030, but the cost difference between green (made from renewable energy) and grey (made from natural gas) hydrogen remains substantial. Closing that gap will require more than government incentives. Large industrial buyers can play a catalytic role by aggregating demand, entering into long-term offtake agreements and signalling future procurement volumes.
These commitments can improve project bankability, attract financing and accelerate cost reductions, particularly under initiatives such as India’s Strategic Interventions for Green Hydrogen Transition (SIGHT). Financiers also have a critical role in supporting first-of-a-kind projects through blended finance, concessional capital and risk-sharing instruments that reduce the cost of early deployment.
From Target Setting to Market Shaping
As Indian corporates set ambitious climate targets, achieving them will require companies to move beyond managing emissions within their own operations. Corporate climate leadership increasingly entails building credible data systems, embedding decarbonisation into procurement and business strategy, investing in supplier transitions and creating demand for low-carbon technologies.
Governments must complement these efforts through policies that strengthen market signals, including carbon pricing, assurance-backed disclosure frameworks, public procurement mandates and support for technology deployment. Research institutions, industry associations and financial institutions also have a critical role to play in developing methodologies, reducing investment risks and scaling solutions across sectors.
Since value chains account for the majority of a company’s emissions, corporate climate targets that do not account for MSME suppliers remain insufficient. MSMEs often lack the capital, technical capacity and market power to decarbonise independently and cannot close that gap alone. They require demand-side investment, financing access, supplier development programmes and long-term procurement commitments from larger companies further up the value chain.
With growing participation in the SBTi ecosystem and globally connected supply chains, the actions of Indian companies have consequences far beyond their balance sheets. If climate action must be commercially viable to be sustainable, the same holds for the MSMEs in their supply chains.
The next phase of corporate climate action in India will therefore be defined less by the targets companies announce and more by the systems they help build. How businesses invest in suppliers, shape demand for low-carbon products and collaborate to overcome shared barriers will determine whether climate ambition translates into implementation. It may even offer lessons for other fast-growing economies navigating the same transition.